
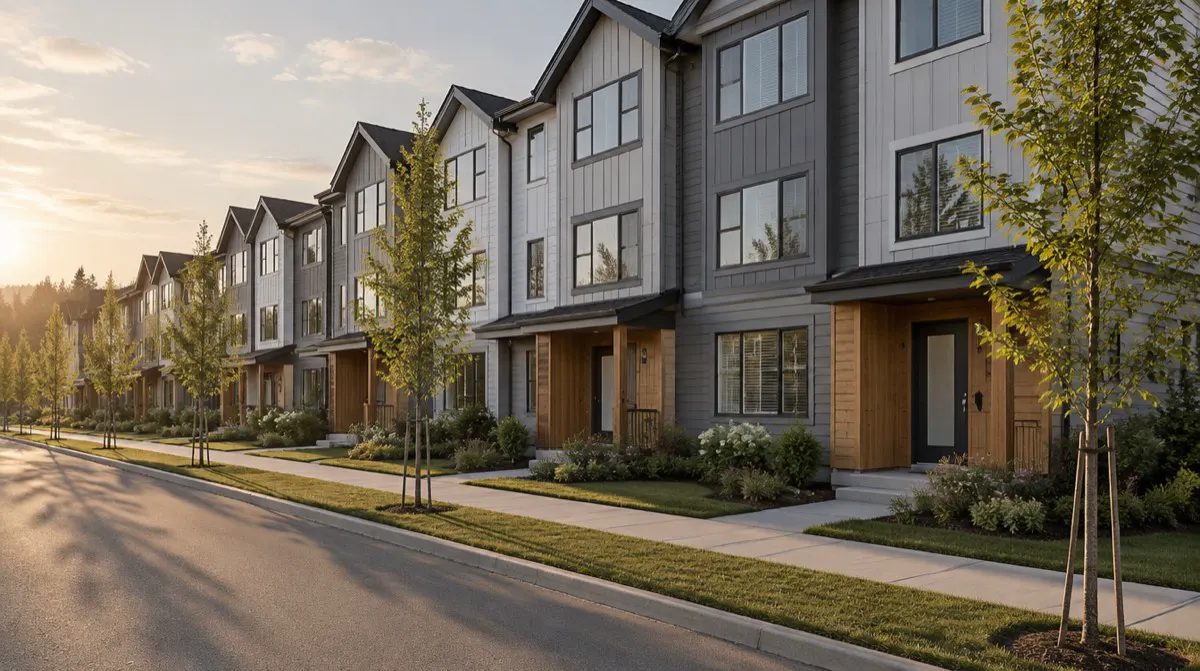
First-time buyers whose income needed explaining before a lender said yes.
How it was arranged: Income documented properly, then a credit union that accepts it.
SampleWhat this involves →

Deal type, area and the problem solved, shown as illustrations of the mortgages we arrange.
Two residential, two construction, two commercial, each one marked as a sample.
First-time buyers whose income needed explaining before a lender said yes.
How it was arranged: Income documented properly, then a credit union that accepts it.
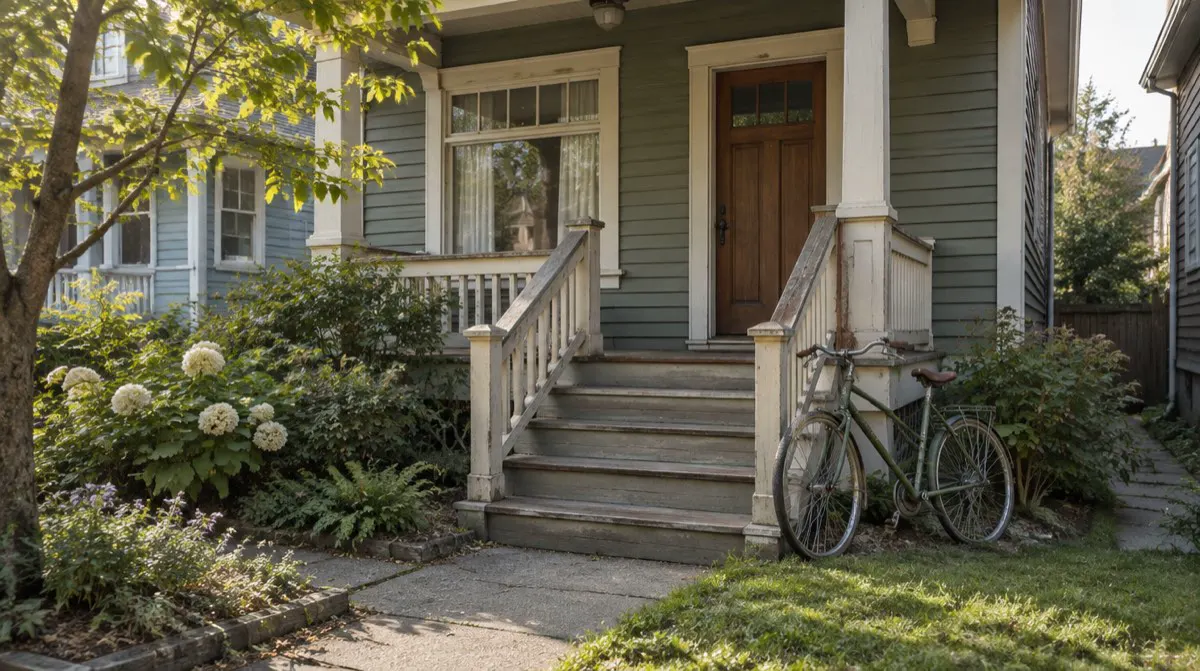
A bank offered only a renewal; a refinance folded in the debt.
How it was arranged: Self-employed income presented the lender's way, and the debts folded into one payment.
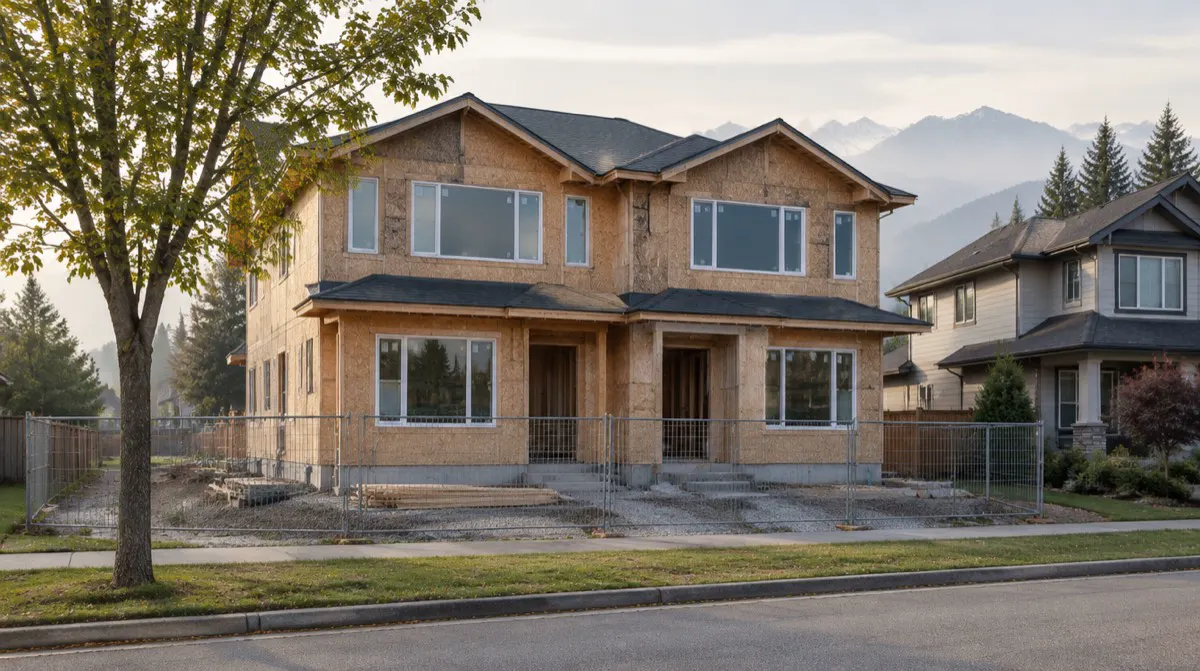
A duplex build the first lender turned down; the second approved it.
How it was arranged: A clearer budget and build schedule, then a second lender who approved it.
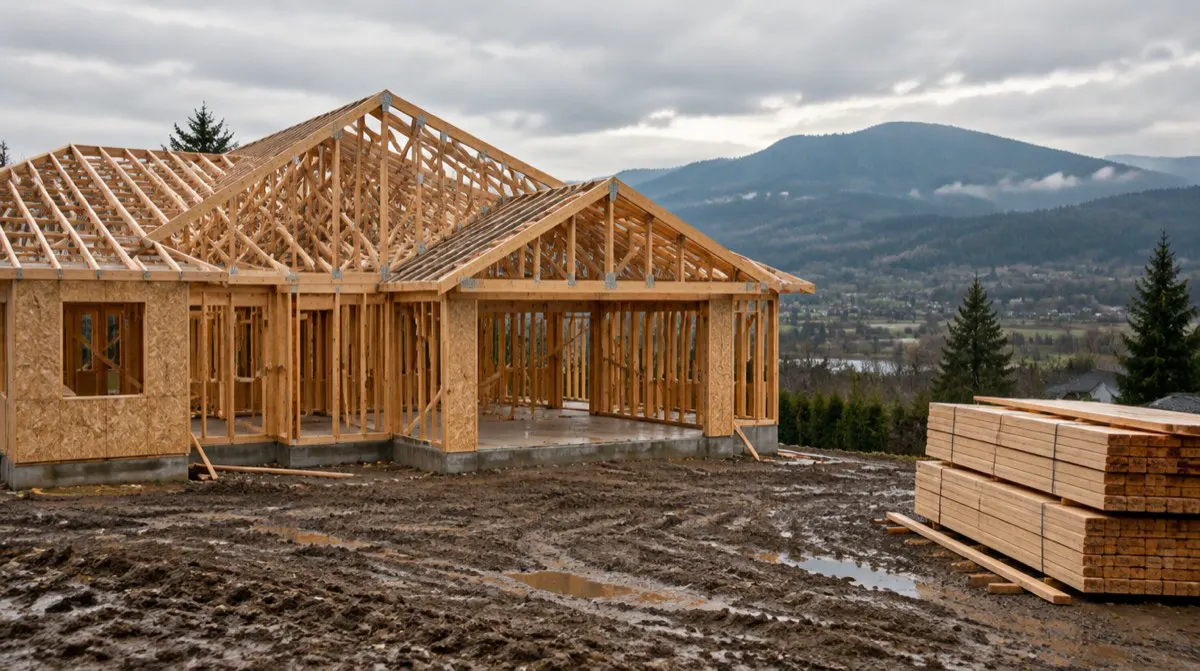
Owner-builders with mixed income, explained to a lender who said yes.
How it was arranged: Both incomes written up together, and stage payments that matched the real build.
A clinic buying its own office, with a credit line arranged alongside.
How it was arranged: The office purchase and a business credit line placed with the same lender.
Leases ending in the same year; the lender was shown the plan.
How it was arranged: Sized on the rent it collects, with the lease renewals set out in writing.
When consented deals replace these samples, each card carries four fields and nothing else: the deal type, the area, the problem that was solved and how long it took from first call to funding. No names, no addresses, no amounts and no rates. A client can recognise their own mortgage; nobody else can.
A card goes up only with the client's written consent, and comes down if they ask. The Done Rite stamp, the small ink mark on a card, appears only on a real deal that has funded. The samples above carry a Sample pill instead, and show no time to fund, because no time has been measured.
The "how it was arranged" line stays on real cards too, in the same plain words: what we did, not what the lender decided.
A free 20-minute call on what's realistic, what it would take, and whether we're the right fit.