
What this rate decision means for you
5 min read

Residential, construction and commercial financing across BC for first-time buyers, self-employed owners and builders, arranged by a licensed broker who explains every option and handles everything through to funding.
Pick the closest match and that page explains what lenders look for, what it costs and how long it takes.
Residential, construction and commercial mortgages, arranged by one team.
Buying, refinancing or renewing a home, including income that takes some explaining.
All residential mortgages
From a custom home to multi-family, arranged before you buy the lot.
All construction financing
Your own premises, income buildings, farmland, plus business credit alongside.
All commercial financingFour things you can count on, whichever kind of mortgage you need.
Sent as each step closes, by text or email.
The same three steps for every mortgage, with a named person looking after yours.
Tell us what you're doing and when. We'll say what's realistic before any paperwork, and who on the team will look after you.
We collect documents first so the application is right the first time, then send it to the lender with a written summary of your situation, not just a form.
The lender sets its conditions (the documents it wants confirmed, and an appraisal of the home), your lawyer or notary prepares the paperwork, and we keep you posted through to the day the money moves.
After funding: a one-page check-in every year, and a heads-up twelve months before your mortgage term ends. How it works in detail
Real reviews from Google, as clients wrote them.
“Sunny always provides exceptional service for me and my clients. … If you're seeking reliable and expert guidance with your financing, I highly recommend reaching out to Sunny.”
“If you're looking for someone to roll up their sleeves and get the job done, look no further! … Give Sunny a shot, you won't be let down.”
“Working with Sunny and his team at Lendrite Mortgages was one of the best decisions my family and I have made. They went beyond the approval to help us build a long-term plan, and made every step feel easy and stress-free. Genuine expertise, real care, and great results. I highly recommend Lendrite.”
Three typical situations, shown as illustrations of how a mortgage comes together.
First-time buyers whose income needed explaining before a lender said yes.
Arranged with: a credit union
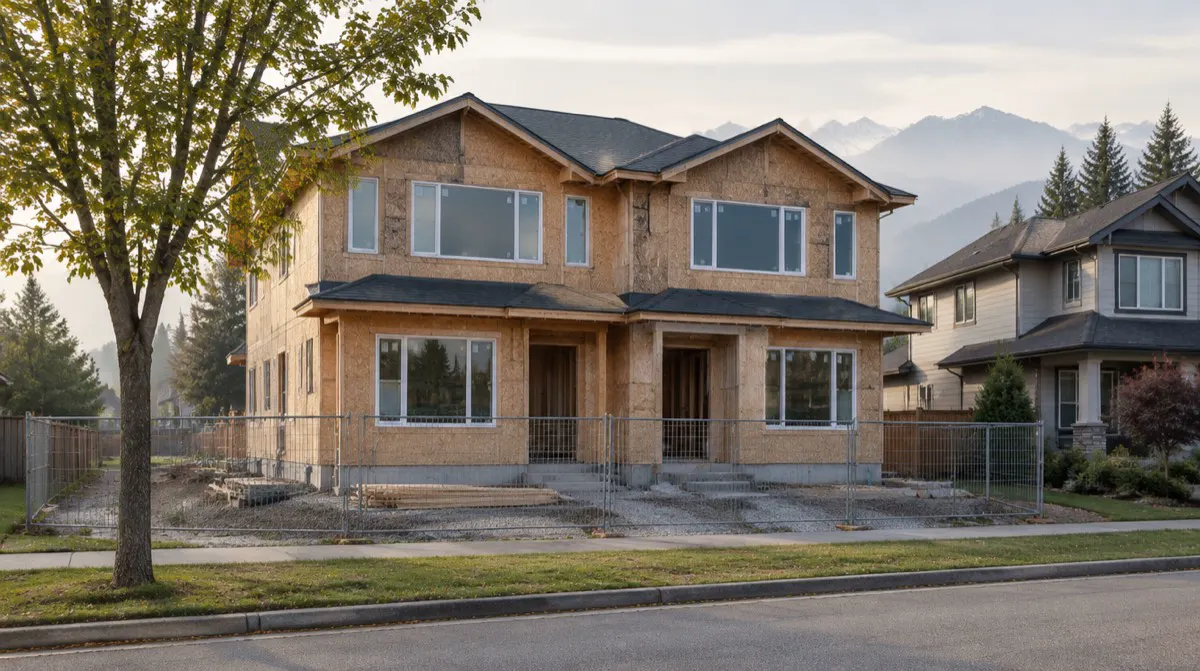
A duplex build the first lender turned down; the second approved it.
Arranged with: a construction lender
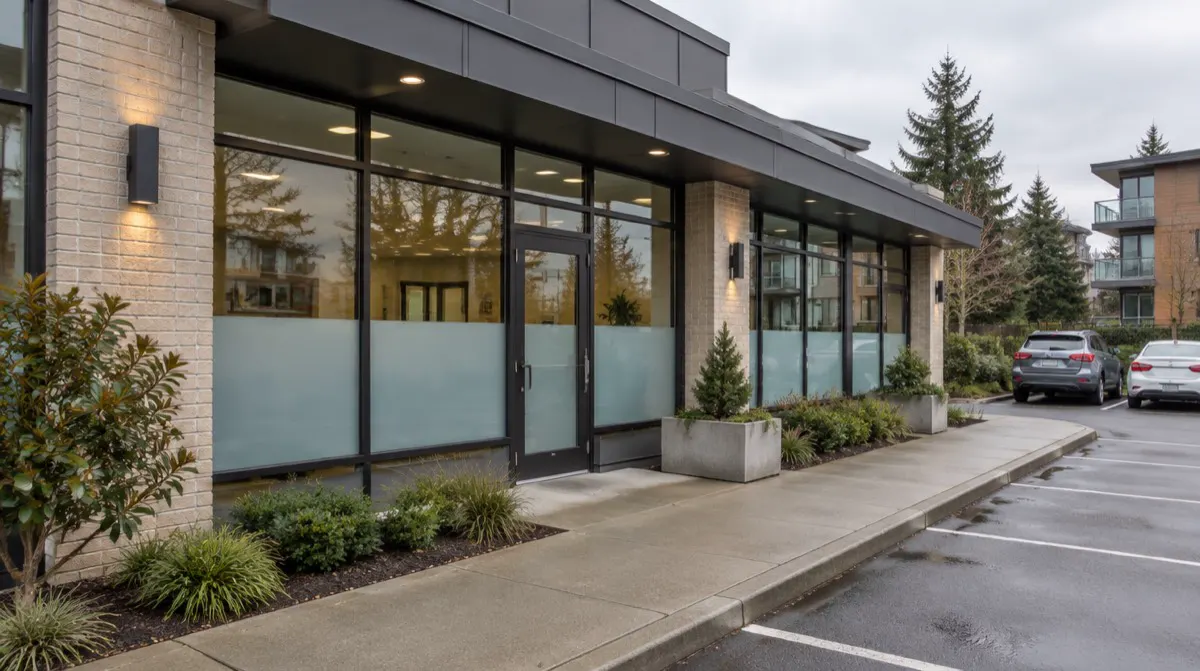
A clinic buying its own office, with a credit line arranged alongside.
Arranged with: a bank, with a business credit line alongside

Market updates when the Bank of Canada moves, and plain guides for each stage of owning a home.
Four questions that come up on almost every first call, with short answers to get you started.
For most residential mortgages the lender pays our fee when the mortgage funds, so you usually pay no broker fee. Where a fee does apply, on commercial, construction and some residential mortgages, we tell you upfront and put it in writing before anything is signed.
Your bank is a fine place to start, and it can offer only its own products. We put offers from banks, credit unions and lenders beyond the big banks beside your bank's, so you see the whole picture. If the right fit is a lender we work with, we handle the application from there; if it turns out to be your bank, we help you read its offer so you know what you are signing.
It depends on the lender, the property and the time of year. Pre-approval is usually the quickest step once your documents are in; purchases, refinances, construction and commercial each run on their own clock, and we tell you the realistic timing upfront.
Yes, and it is a big part of what we do. Some banks have good programs for business owners, and there are lenders beyond the big banks that look at what your business actually brings in, through its bank statements and contracts, rather than only the income on your tax returns. We start with how your business earns and match it to the lender whose program fits; the documents follow from that.
A free 20-minute call on what's realistic, what it would take, and whether we're the right fit.